Coverage
Hurricane Insurance in Florida
For Northeast Florida homeowners comparing wind coverage, the hurricane deductible sets what you pay after a storm. We price a 2%, 5%, and 10% deductible across several A-rated carriers and show each one in dollars.
 Deductibles in Dollarsnot percentages on a page
What’s Covered
What Florida Hurricane Coverage Pays For
Wind Damage
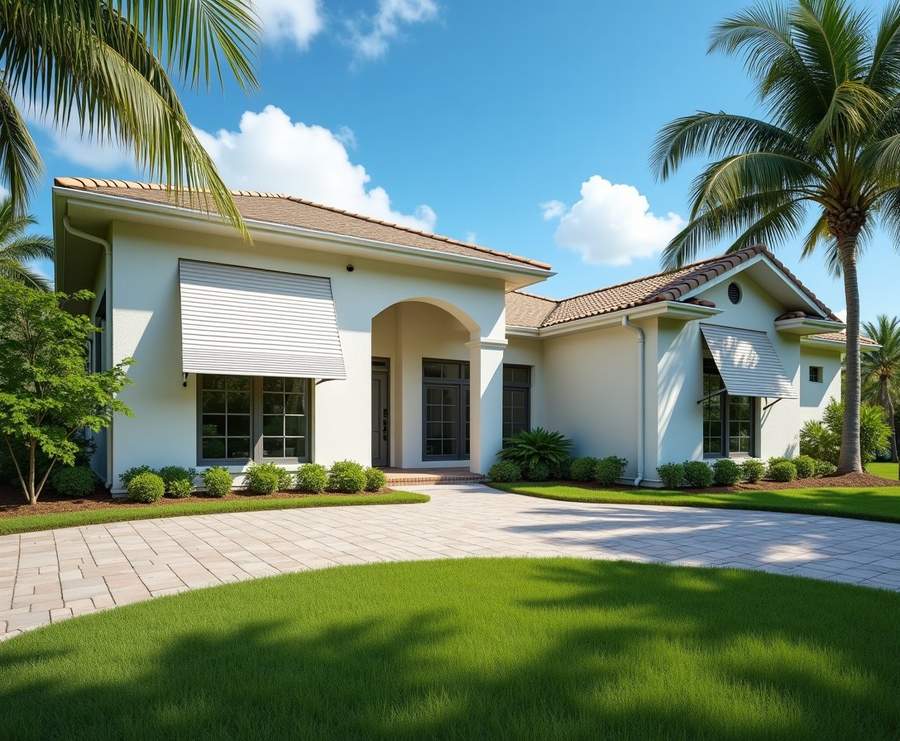
Roof, walls, windows, and doors torn or broken by hurricane wind. Rain that gets inside is covered only when the wind first opens a hole in the building, so roof and window strength count.
Hurricane Deductible
Carriers must offer hurricane deductibles of 2%, 5%, and 10% of Coverage A, plus a flat $500 option on homes insured under $250,000. On a $750,000 home, those percentages equal $15,000, $37,500, or $75,000.
Calendar-year Rule
Florida applies the hurricane deductible once per calendar year rather than once per storm. A second hurricane that year uses whatever deductible remains, or your all-other-perils deductible if that is higher.
Other Structures
Fences, detached garages, and sheds damaged in the same hurricane. Those repairs count toward the same calendar-year hurricane deductible as the house rather than starting a new one.
Loss of Use
Rent, hotel stays, and added living costs while hurricane damage leaves the house unlivable during repairs. Keep receipts from the day you leave, since the claim is paid against what you spend, up to the policy limit.
Mitigation Credits
Florida law requires carriers to discount premiums for wind-resistant features such as roof-to-wall straps, roof deck attachment, and opening protection. A current OIR-B1-1802 inspection form is how you prove the home has them.
Wind-only Policies
When a private carrier excludes wind, Citizens can write a wind-only policy in its wind-eligible coastal areas, paired with a separate policy for the other perils. We check eligibility by address.
Debris Removal
Clearing storm debris, and removing trees that fall on the house or another covered structure, up to the debris limit on your form. Limits vary by carrier, so we note the figure on each quote.
Who It’s For
Who Should Compare Hurricane Deductibles
Homes Built Before 2008
Homestead owners with low or moderate incomes and homes insured for $700,000 or less may qualify for a My Safe Florida Home grant toward wind upgrades.
Homes Insured Over $1 Million
Between $1 million and $3 million in dwelling coverage, a carrier may offer 3% in place of 2%. At $3 million or more, 2% need not be offered.
Owners After a Hurricane Claim
After a hurricane loss, a lower deductible you choose does not take effect until January 1 of the following year.
Owners With Older Wind Reports
Florida revised the wind mitigation form on April 1, 2026, adding questions on design wind speed region and roof slope. Forms stay valid up to five years.
Our Process
How We Price Your Deductible Options
Send Your Wind Mitigation Form
Send your declarations page and any OIR-B1-1802 form signed within the past five years. If you do not have one, we explain which licensed professionals can complete the inspection.
We Quote Three Deductible Levels
Each A-rated carrier we vet prices hurricane deductibles at 2%, 5%, and 10% for your home, and we convert every option to dollars so each premium sits beside the amount you would carry.
Choose the Number You Can Cover
A licensed agent goes over each option with you, including how the calendar-year rule works. You pick the deductible you could pay after a storm, and we bind that policy.
“Absolutely thrilled with the service Anna provided for both our car and homeowners insurance. She went above and beyond for us and our savings was remarkable!”
Dawn DiBrino · Google review
Common Questions
Florida Hurricane Coverage Questions
A Florida hurricane deductible applies from the moment the National Hurricane Center posts a hurricane warning anywhere in the state until 72 hours after every hurricane watch and warning for Florida has ended, under s. 627.4025, F.S. Wind damage from a storm the Hurricane Center never classified as a hurricane generally falls under your all-other-perils deductible instead. Some carriers use a broader named-storm deductible, so check the wording on your policy.
Florida hurricane coverage pays for rain damage inside the house only when the storm’s wind first creates an opening in the roof, walls, or windows that lets the rain in. That rule comes from s. 627.4025(2), F.S. Rising water from storm surge or flooding is a separate peril that needs a flood policy, which we quote alongside your wind coverage.
Florida homeowners pay one hurricane deductible per calendar year, not one per storm. Under s. 627.701(5), F.S., a second hurricane that year uses whatever remains of the hurricane deductible or your all-other-perils deductible, whichever is greater. If you lower your hurricane deductible after a hurricane loss, the lower amount waits until January 1 of the following year.
Yes, a Florida hurricane deductible can go above 10%, but on a home valued under $500,000, every named insured must write out, sign, and date a statement accepting that amount, and the mortgage holder must approve it in writing, under s. 627.701(4)(d), F.S. Any policy with a separate hurricane deductible carries a warning about high out-of-pocket costs in 18-point bold type, and the declarations page shows the deductible in dollars.
Under s. 627.711(2), F.S., the OIR-B1-1802 wind mitigation form can be signed by a licensed home inspector with hurricane mitigation training, a building code inspector, a general, building, or residential contractor, an engineer, or an architect. The current version took effect April 1, 2026, has nine questions, and accepts FORTIFIED Roof, Silver, and Gold certificates as proof for several features. A completed form stays valid up to five years if the home has not materially changed.
As of October 6, 2026, My Safe Florida Home was accepting applications, with grants limited to low- and moderate-income homestead owners of site-built homes built before 2008 and insured for $700,000 or less. Under s. 215.5586, F.S., the state pays $2 for every $1 the owner puts in, up to $10,000, and low-income owners pay no match. Grants cover opening protection, roof-to-wall connections, roof deck attachment, and secondary water resistance.
Get Started
Price My Deductibles
Tell us your dwelling limit and attach any wind report. A licensed agent sends each deductible option in dollars, carrier by carrier, within one business day.